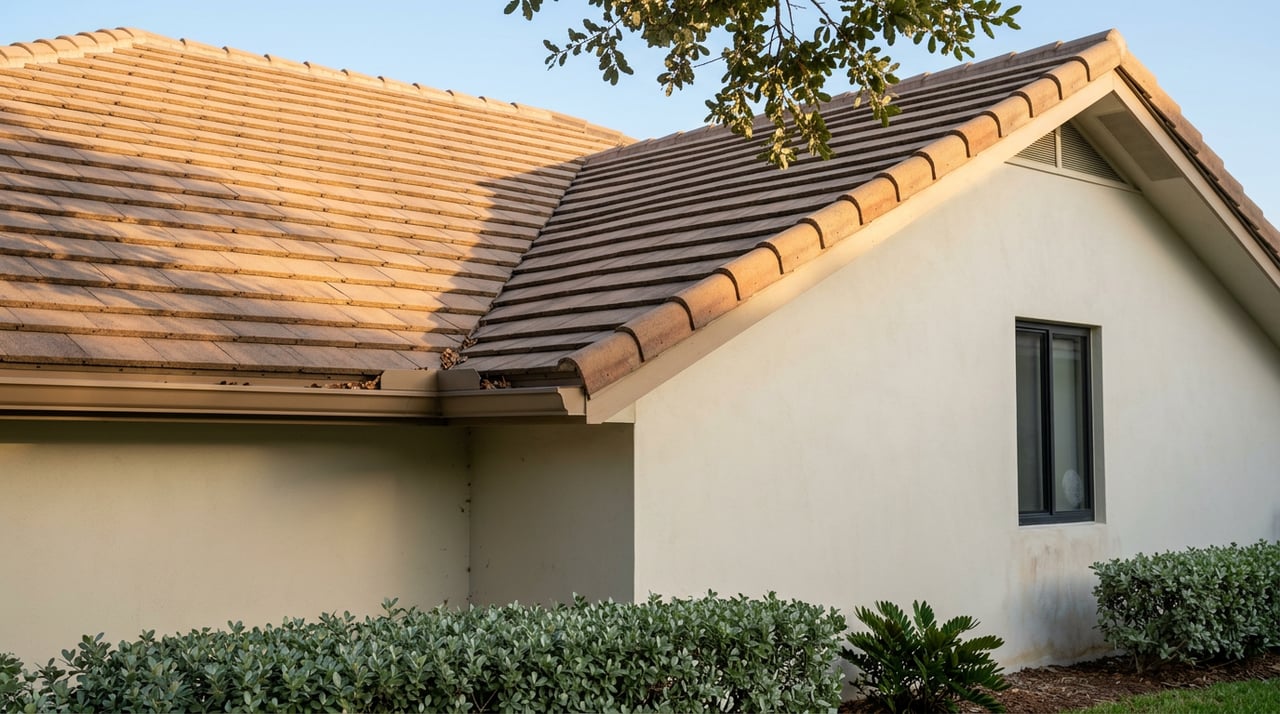
Why would two nearly identical villas, three doors apart in the same Boynton Beach community, get opposite news from their insurers in the same month? One seller gets a renewal letter with no roof mention at all. The other gets a non-renewal notice citing roof age, even though both roofs went on within a year or two of each other back in the 1980s.
The honest answer has nothing to do with luck and everything to do with a law that a lot of people in Palm Beach County believe passed this year. It didn't. If you're buying, selling, or holding a roof that's closing in on its third decade in one of Boynton Beach's older communities, that distinction is worth understanding before you sign anything.
The Law That Didn't Pass
Search "Florida roof age law 2026" right now and you'll find plenty of pages telling you that Senate Bill 808 and its House companion, HB 815, took effect on July 1 and now bar insurers from refusing to write or renew a policy based on roof age alone, across every type of residential property. That's a clean, reassuring story. It's also not what happened.
Both bills died in the House Insurance and Banking Subcommittee on March 13, 2026, months before their proposed effective date. You can confirm this directly on the Florida Senate's own bill tracker for HB 815. They never reached a floor vote, never got a governor's signature, and never became law. The confusion seems to come from the fact that both bills listed July 1, 2026 as a proposed effective date in their original text, and that date has been repeated across enough roofing and insurance sites that it now reads like settled fact.
What's actually in force is the older rule, Florida Statute 627.7011, dating to the 2022 and 2023 insurance reforms. It says an insurer can't refuse to issue or renew a homeowner's policy solely because a roof is under 15 years old. Between 15 and 25 years, the insurer can require a certified inspection, and if that inspection documents at least five years of remaining useful life, age alone still can't be used to deny coverage. Past 25 years, most private carriers step back and Citizens Property Insurance becomes the practical option for a lot of owners. That's the actual rulebook governing every roof conversation happening in Palm Beach County right now, not the broader version that almost passed.
Why One Zip Code Feels This More Than Most
This matters more in Boynton Beach than in a lot of neighboring cities because of how the city was built, not because of anything unusual about its insurance market. Communities like Leisureville and Hunters Run went up in concentrated construction waves through the 1970s, 80s, and into the 90s. That means hundreds of roofs installed within a few years of each other are now aging through the same 15-year and 25-year thresholds at roughly the same time, community-wide.
A roof's material decides how that threshold actually lands. Asphalt shingle, the most common covering on the era's smaller homes and villas, tends to perform for 15 to 20 years in South Florida's heat and UV exposure, sometimes less. Concrete and clay tile, common on the larger estate-style homes in communities like Pine Tree, Hunters Run, and Valencia Grand, can carry the tile itself for 30 to 50 years even though the waterproof underlayment beneath it typically wears out well before the tile does. A 2026 local roof replacement estimate puts a basic architectural-shingle job at around $8,500, a typical concrete tile job on a 2,000 square foot home at $20,000 to $28,000, and larger estate homes in those same communities at $35,000 to $60,000 or more.
| Roof material | Typical lifespan in South Florida | Insurance scrutiny point |
|---|---|---|
| Asphalt shingle | 15 to 20 years | Certified inspection often required after 15 years |
| Concrete or clay tile | 30 to 50+ years (tile itself) | Underlayment failure at 15 to 25 years can trigger the same review |
| Metal (standing seam) | 40 to 70 years | Rarely triggers age-based review before other systems do |
That table is the reason a home's listing price tells you almost nothing about its insurability. A $300,000 tile-roofed home in Hunters Run and a similarly priced shingle-roofed home in Leisureville can be sitting on completely different insurance timelines, even if both were built the same decade.
The Difference Between Your Roof and the Roof Your HOA Owns
If you're looking at a villa or condo rather than a detached single-family home, the roof question shifts entirely.
A buyer's agent should be asking for the association's most recent insurance renewal terms and reserve study before writing an offer, not just checking the individual unit's condition. A well-run building with a fully reserved roof replacement fund is a very different purchase than one where the board is still deciding how to pay for it.
What Actually Moves Your Premium
Age alone doesn't set your rate. Documentation does. Florida Statute 627.0629 requires insurers to credit verified wind-mitigation features, things like a current-code roof covering and a secure roof-to-wall attachment, and a fresh, code-compliant reroof is the natural moment to capture those credits. Local roofing estimates put the windstorm portion of a premium reduction at 25 to 45 percent after a documented, code-compliant reroof with a wind mitigation inspection, which itself typically runs $75 to $150.
For a seller, that means a roof replaced or seriously repaired in the last several years, with the permit and wind mitigation paperwork in hand, is a stronger selling point than the roof's calendar age suggests. For a buyer, it means asking for that paperwork before assuming a 20-year-old roof is a deal breaker. It might not be, if someone already did the work to document it.
Before You List or Make an Offer
- If you're selling a home with a roof past 15 years, schedule a four-point and wind mitigation inspection before you list, not after an offer comes in. A documented, current report in hand shortens the financing timeline for your buyer.
- If you're buying a detached home in an older Boynton Beach community, ask for the roof's install date and any permits for repairs, not just its visible condition.
- If you're buying into a condo or villa community, ask for the association's reserve study and current master insurance renewal terms.
- Don't assume a new law fixed the roof-age question this year. The rule you're working under is Florida Statute 627.7011, not a broader version that stalled in committee.
A Few Direct Questions
Does a roof older than 15 years automatically get declined for coverage? No. Florida Statute 627.7011 requires the insurer to allow a certified inspection, and if that inspection shows at least five years of remaining useful life, the insurer can't deny or non-renew based on age alone.
Does replacing part of a roof reset its insurance age? It depends on how much of the roof is affected and what your specific carrier's underwriting guidelines say. A full, permitted replacement is the clearest way to reset the age question and pick up wind mitigation credits at the same time.
Is there a new law coming that expands these protections? Not as of this writing. SB 808 and HB 815 proposed exactly that, including adding roof consultants as authorized inspectors, but both died in committee on March 13, 2026.
Roof age isn't a reason to avoid buying or selling in Boynton Beach's older communities. It's a reason to ask the right questions before the financing timeline gets tight. If you're weighing a purchase or a listing in Leisureville, Hunters Run, or anywhere else in Boynton Beach where the roofs are getting to that age, Varsha Chandra has spent two decades walking Palm Beach County buyers and sellers through exactly this kind of detail. Schedule a free consultation to talk through what your specific address needs before you write the offer or sign the listing agreement.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.